Trading Session Overview
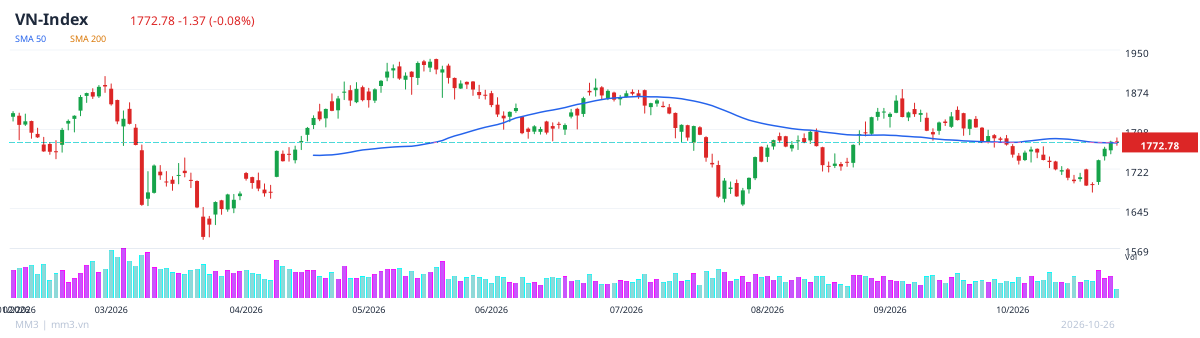
During the mid-session on October 26, 2026, the VN-Index stood at 1,772.8 points, down 1.4 points or -0.1%, indicating that the market is in a short-term state of equilibrium but has not yet confirmed a clear trend. Overall market liquidity remained high, with 258.1 million shares matched on HOSE, reflecting participation by cash flow that is nonetheless selective. Market breadth continued to diverge sharply as capital concentrated in a few large-cap stocks and high-liquidity groups.
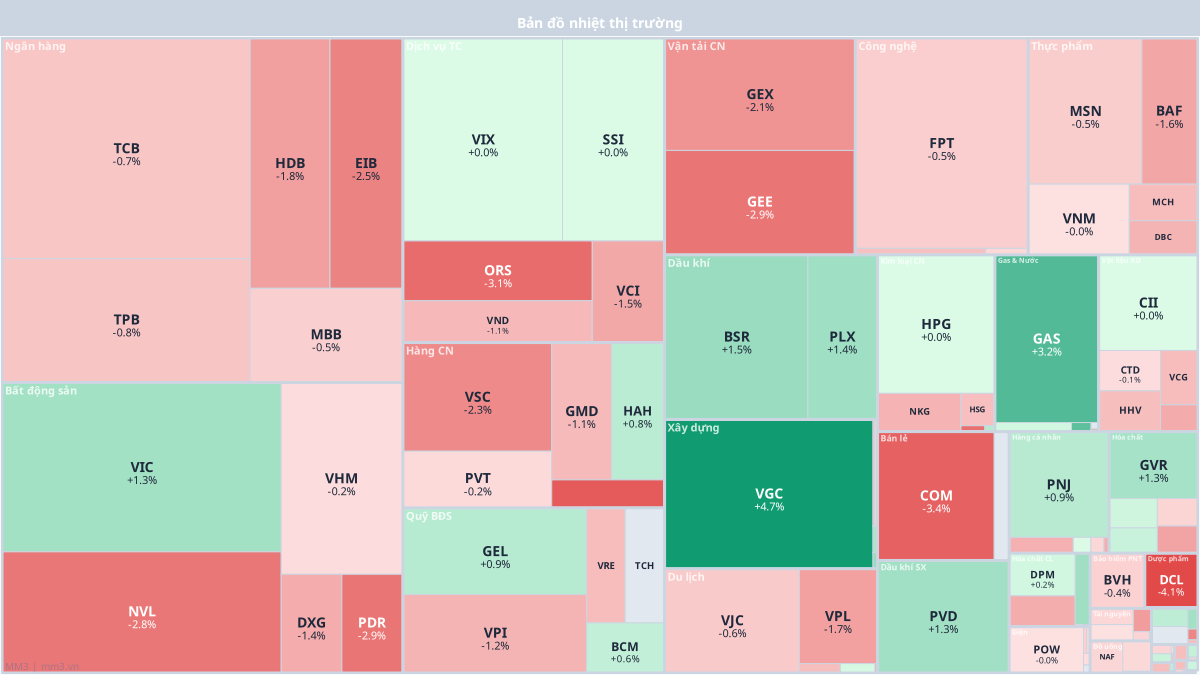
On HOSE, the highly liquid stocks included NVL with 18.7 million shares, VIX with 14.6 million shares, and TPB with 13.6 million shares. On the upside, several tickers such as MDG, VCA, VNG, ABT, and VTB rose in the range of 6.6% to 7.0%, underscoring that a high degree of divergence remained the defining feature of this session.
Notable Stock Groups
Among the leading names, VIC gained 1.3% to 239,600 VND and was one of the few large caps to stay in positive territory as the broader market moved sideways. Conversely, NVL fell 2.8% to 10,300 VND despite leading the market in liquidity, showing that profit-taking pressure remained evident. VIX was nearly flat at 12,700 VND with 14.6 million shares traded, while TPB declined 0.8% to 12,900 VND.
Among the strong performers in the basket, VGC rose 4.7% to 46,600 VND, GAS climbed 3.2% to 80,800 VND, BSR increased 1.5% to 29,500 VND, and PLX advanced 1.4% to 35,950 VND. On the other side, EIB dropped 2.5% to 17,400 VND, PDR fell 2.9% to 11,800 VND, and VSC declined 2.3% to 14,750 VND.
| Ticker | Price | Change | Volume |
|---|---|---|---|
| NVL | 10,300 | -2.8% | 18.7 million |
| VIX | 12,700 | 0.0% | 14.6 million |
| TPB | 12,900 | -0.8% | 13.6 million |
| VIC | 239,600 | 1.3% | 1.1 million |
| VGC | 46,600 | 4.7% | 3.8 million |
Sector Analysis
The banking sector faced fairly clear correction pressure, with TPB down 0.8%, HDB down 1.8%, EIB down 2.5%, MBB down 0.5%, and TCB down 0.7%. This development suggests that cash flow has not yet truly returned to the traditional leading group, while support from individual stocks remains limited.
In real estate, the trend of divergence remained very strong. VIC rose 1.3% in contrast to NVL, which fell 2.8%, PDR, which dropped 2.9%, and DXG, which declined 1.4%. This reflects high selectivity, with the market favoring stocks that have their own stories and better liquidity.
The oil and gas sector was a relative bright spot, with BSR up 1.5%, PLX up 1.4%, and GAS up 3.2%. Meanwhile, the construction and materials group showed improvement in several names such as VGC, which rose 4.7%, DHA, up 1.1%, and ACC, up 1.6%. Conversely, the financial services group remained highly divergent, with VIX nearly flat, SSI edging up 0.0%, while ORS fell 3.1%, VND declined 1.1%, and VCI dropped 1.5%.
| Industry | Notable Tickers | Developments |
|---|---|---|
| Banking | TPB, HDB, EIB, MBB, TCB | Broadly declining |
| Real Estate | VIC, NVL, PDR, DXG | Strongly divergent |
| Oil & Gas | BSR, PLX, GAS | Positive |
| Construction | VGC, DHA, ACC | Improving |
| Financial Services | VIX, SSI, ORS, VND, VCI | Selective |
Outlook
From a technical standpoint, the market remains in a consolidation zone as the VN-Index has yet to fully break out of its equilibrium state. If cash flow continues to stay in high-liquidity groups such as NVL, VIX, and TPB, the oscillation may persist for some time before a clearer trend forms. Conversely, the simultaneous divergence among core groups suggests that short-term volatility risks remain present.
A notable signal is that several stocks with high composite scores, such as DHC at 75.7 points, FDC at 72.3 points, ADP at 70.6 points, DTT at 70.6 points, and HAH at 70.1 points, are showing a more positive technical foundation than the broader market. However, the overall market context still requires further confirmation of how widely cash flow is spreading. In the short term, the 1,770-point level on the VN-Index remains a key threshold to watch closely, along with the potential for improved breadth in leading groups.