Market Session Overview
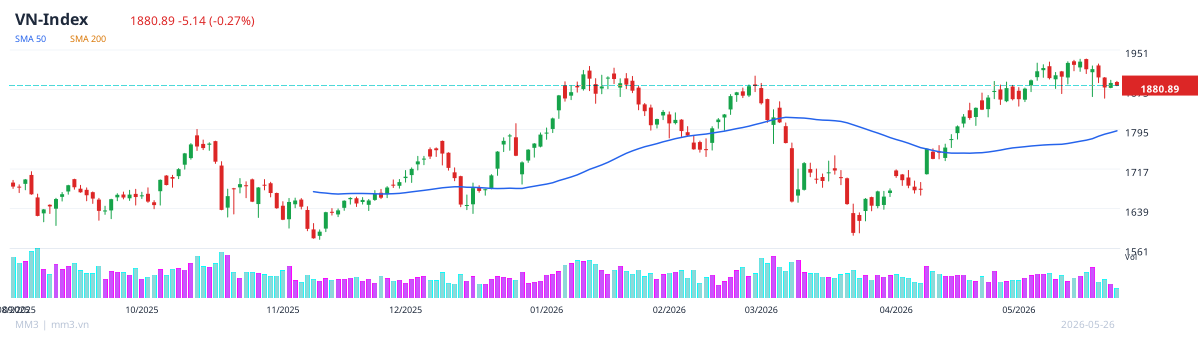
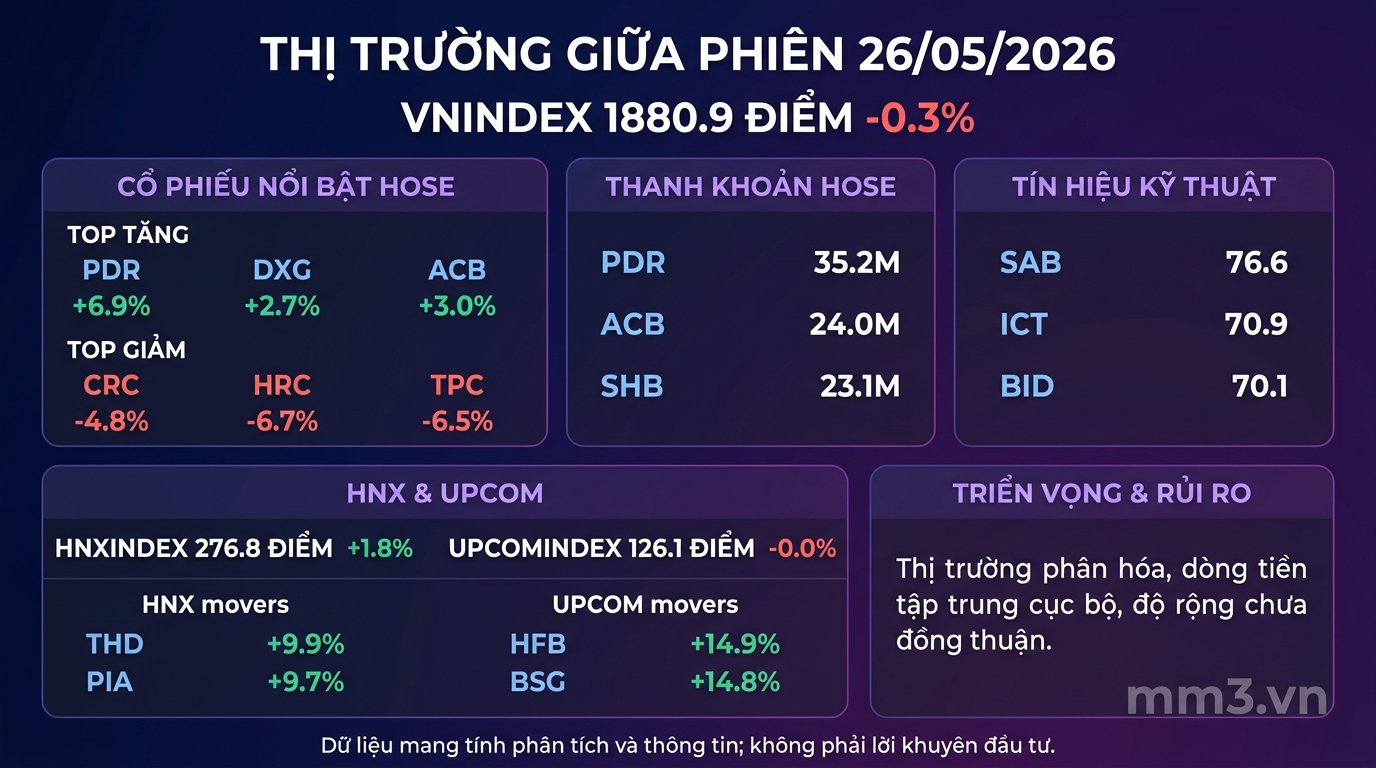
At midday on May 26, 2026, the Vietnamese stock market continued to trade in a choppy, sideways range. VNINDEX stood at 1,880.9 points, down 0.3%, reflecting that short-term profit-taking pressure remains present but not strong enough to signal a clear weakening.
Market-wide liquidity remained at a fairly healthy level, while cash flow continued to concentrate locally in a handful of leading stocks. This suggests the market has not yet formed broad-based consensus on upward momentum, but technical signals in prominent stocks still support a short-term recovery.
Key Index Performance
| Index | Value | Change | Assessment |
|---|---|---|---|
| VNINDEX | 1,880.9 | -0.3% | Sideways |
| HNXINDEX | 276.8 | +1.8% | Clearer recovery |
| UPCOMINDEX | 126.1 | -0.0% | Nearly flat |
The data shows a clear divergence across exchanges: HNXINDEX rose 1.8% to 276.8 points, while UPCOMINDEX was nearly flat at 126.1 points. This reinforces the view that cash flow is being selective rather than spreading across the entire market.
Notable Stock Groups
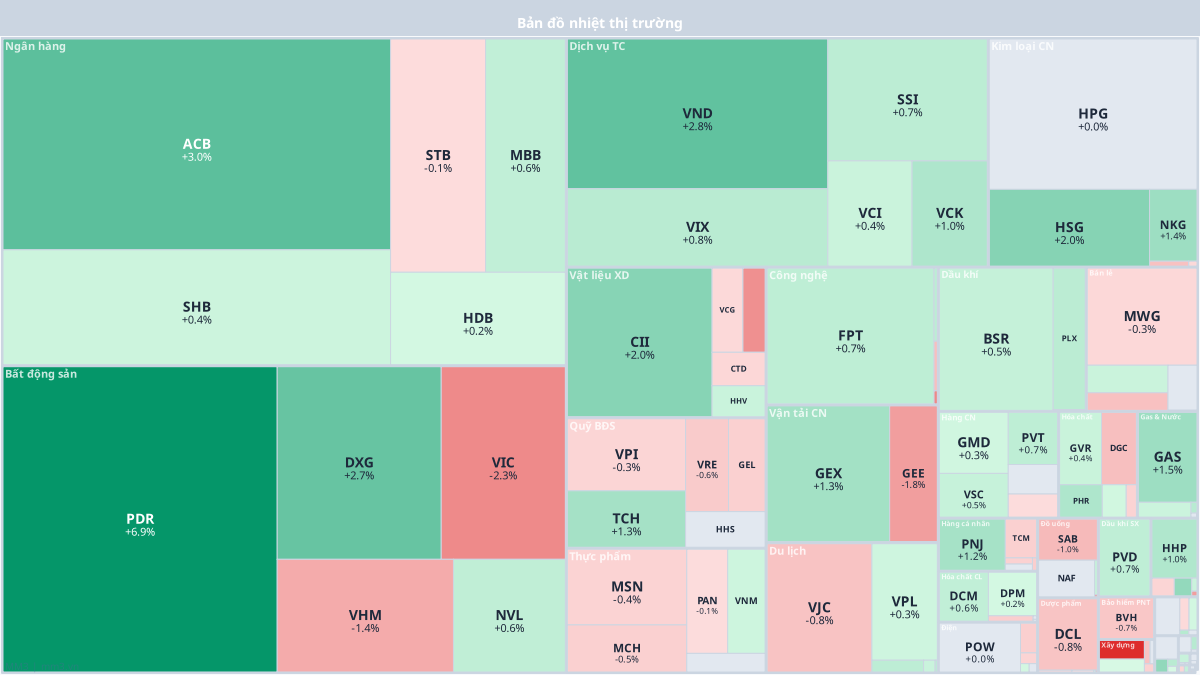
Among gainers, the most prominent on HOSE was PDR, up 6.9% with trading volume of 35.2 million shares, indicating very strong concentrated buying demand. Meanwhile, ACB rose 3.0% with a transaction value of VND 581.7 billion, and DXG gained 2.7% with trading volume of 14.8 million shares.
On the other side, several stocks remained under selling pressure, including CRC, down 4.8%, HRC, down 6.7%, and TPC, down 6.5%. This shows that the market's upward momentum is not yet uniform, and sector divergence remains quite pronounced.
Notable HOSE Stocks
| Group | Ticker | Change | Liquidity/Notes |
|---|---|---|---|
| Gainers | PDR | +6.9% | 35.2 million shares |
| Gainers | ACB | +3.0% | VND 581.7 billion |
| Gainers | DXG | +2.7% | 14.8 million shares |
| Losers | CRC | -4.8% | Rising selling pressure |
| Losers | HRC | -6.7% | Among deep decliners |
| Losers | TPC | -6.5% | Among deep decliners |
Sector Analysis
The banking sector continues to serve as a key support, with ACB, SHB, MBB, and HDB all maintaining gains. Meanwhile, real estate remains a hotspot for cash flow, with PDR leading in liquidity, while DXG also recorded a notable increase.
The financial services sector maintained relatively high activity, with VND, VIX, SSI, and VCI all seeing significant trading. Conversely, the food sector and some industrial stocks still showed signs of correction, contributing to the market's lack of broad-based consensus.
Notable HOSE Liquidity
- PDR: 35.2 million shares
- ACB: 24.0 million shares
- SHB: 23.1 million shares
HNX and UPCOM: Signs of Recovery but Still Divergent
On HNX, the strong uptrend group continued to stand out, with THD rising 9.9% and PIA up 9.7%. Liquidity was also concentrated in SHS and CEO, indicating that money flow is favoring stocks with large trading volumes.
On UPCOM, the divergence was even sharper, with HFB gaining 14.9% and BSG up 14.8%, while several other stocks fell steeply. This suggests short-term risk remains, especially among stocks with low liquidity.
Positive technical signal group
| Ticker | Composite score | Signal |
|---|---|---|
| SAB | 76.6 | Neutral RSI, positive MACD and EMA |
| ICT | 70.9 | Neutral RSI, positive MACD and EMA |
| BID | 70.1 | Neutral RSI, positive MACD and EMA |
From a technical standpoint, stocks such as SAB, ICT, and BID are maintaining high composite scores, suggesting the recovery trend still has room to run if no fresh selling pressure emerges. This group is worth watching as money flow remains selective.
Outlook and risks
The short-term scenario still leans toward divergence across sectors and individual stocks. If VNINDEX holds the 1,880-point zone and liquidity does not weaken further, the rebound could continue, focusing on stocks with strong money flow and favorable technical signals.
Conversely, if profit-taking pressure spreads again, the nearby support zone will play an important role in sustaining the market's momentum. Investors should pay close attention to market breadth, liquidity in leading groups, and the performance of large-cap stocks in the coming sessions.
The data is for analytical and informational purposes only; it does not constitute investment advice.