Trading Session Overview
The trading session on 10/04/2026 closed with mixed results, but with a generally positive tilt. VNINDEX rose 13.32 points (+0.8%) to 1,750.00 points, while HNXINDEX gained 0.93 points (+0.4%) to 251.91 points, and UPCOMINDEX edged down 0.12 points (-0.1%) to 127.38 points. Market-wide liquidity remained elevated, reflecting that capital flows continued to move actively across different stock groups.
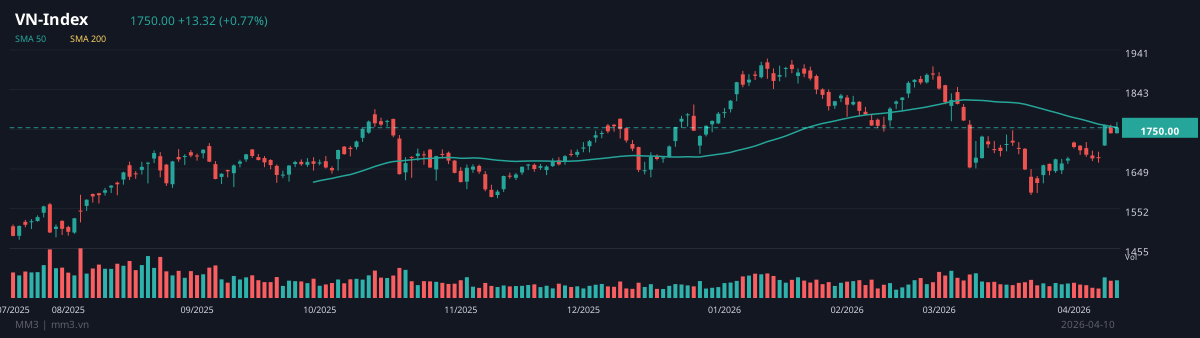
Market breadth on the HOSE exchange showed an uneven balance: strong gains were concentrated in a handful of individual stocks, while selling pressure persisted across many mid- and small-cap groups. This backdrop suggests the short-term trend remains intact, but capital flows have not yet spread evenly across the entire market.
Notable Stock Groups
HOSE: Oil and Gas and Select Speculative Stocks Break Out
Among the biggest gainers, AGM rose 11.1% to 2,000 VND per share, BSR climbed 7.0% to 26,750 VND per share, and TNC increased 6.9% to 29,400 VND per share. On the other side, DCL fell 7.0% to 41,850 VND per share, PNC dropped 7.0% to 26,000 VND per share, and HRC declined 6.9% to 43,750 VND per share.
This movement clearly reflects thematic capital rotation rather than a broad-based, consensus uptrend. The oil and gas sector remained the focal point, with BSR and PLX both posting solid gains, while some pharmaceutical and media stocks faced heavy profit-taking pressure.
Liquidity Concentrated in Leading Stocks
In terms of liquidity, SHB led with 105.59 million shares, followed by VIX with 41.34 million shares and HPG with 35.47 million shares. The banking, securities, and steel sectors remained the largest recipients of capital, indicating investors' interest in stocks capable of leading the market's momentum.
- SHB: 105.59 million units matched.
- VIX: 41.34 million units matched.
- HPG: 35.47 million units matched.
Sector Analysis
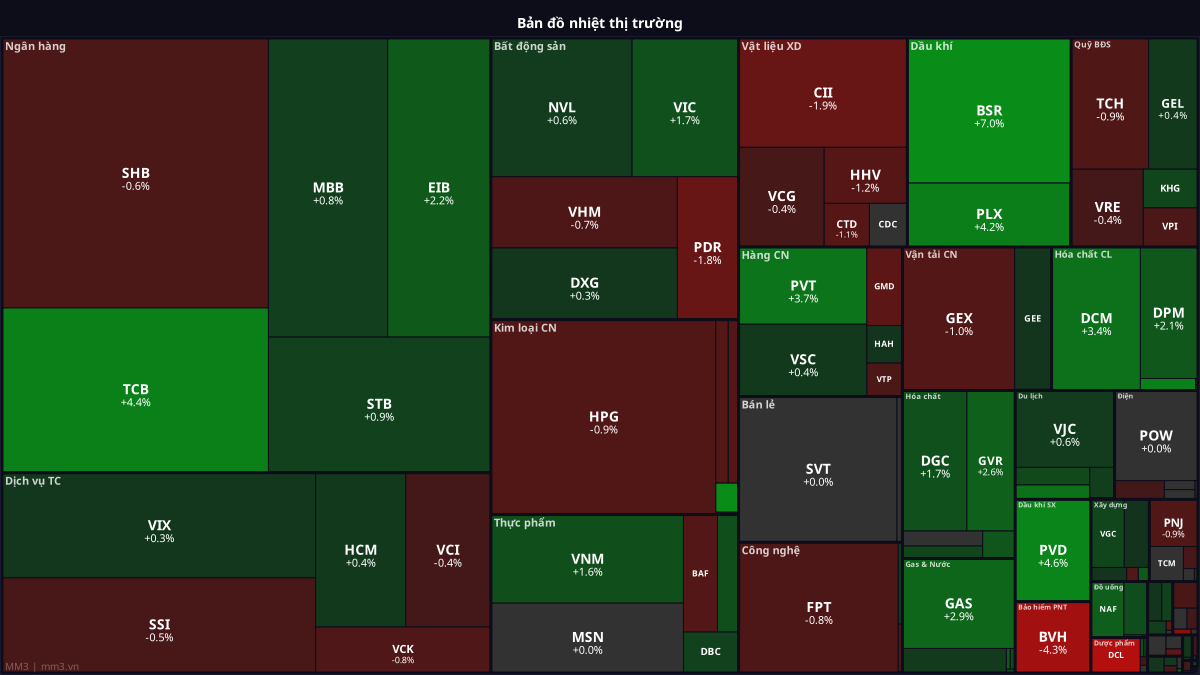
The sectors leading this session included oil and gas, chemicals, banking, and food. On the other side, selling pressure emerged in pharmaceuticals, insurance, construction materials, and media. The divergence among sectors suggests the market remains in a stock-selection phase rather than confirming a synchronized breakout.
Specifically, the oil and gas sector stood out with BSR up 7.0%, PLX up 4.2%, and PVD up 4.6%. The chemicals sector also stayed in positive territory, with DCM up 3.4%, DPM up 2.1%, and BFC up 4.3%, while the pharmaceutical sector came under heavy pressure as DCL dropped its full 7.0% daily limit.
Notable Technical Signals
Stocks showing positive technical signals continued to record high composite scores. DSE reached 82.4 points with an RSI of 54, a rising MACD, and a rising EMA; VIX reached 75.4 points with an RSI of 62 and a rising MACD, but its EMA is still declining; SFI reached 73.8 points with an RSI of 54, a rising MACD, and a rising EMA.
- DSE: composite score of 82.4, with a clearly improving trend.
- VIX: composite score of 75.4, with good momentum, but the medium-term trend is not yet fully aligned.
- SFI: composite score of 73.8, with MACD and EMA signals moving in sync.
From a technical perspective, stock groups with both MACD and EMA trending positively tend to sustain rebounds for longer. However, while market breadth remains divided, individual upward moves need to be viewed in the context of liquidity and confirmation from leading groups.
Developments on Other Exchanges
On HNXINDEX, the index rose 0.4% to 251.91 points. Notable gainers included GLT (+10.0%), DHT (+9.8%), and PHN (+9.7%), while KSQ fell 13.3%, SDA dropped 10.0%, and HHC declined 9.9%.
On UPCOMINDEX, the index slipped 0.1% to 127.38 points, but individual stock swings were very large. ONW climbed 38.9% and PTE rose 35.7%, while PJS plunged 39.9% and SPH fell 32.0%, showing that divergence risk among small-cap stocks remains high.
Outlook and Risks
In the short term, the 1,750-point level on VNINDEX remains an important benchmark to watch, both psychologically and technically. If liquidity holds and capital continues rotating among banking, oil and gas, chemicals, and securities, the positive trend could be further reinforced.
Conversely, the main risk lies in market breadth not yet showing genuine consensus, along with profit-taking pressure in overheated gainers. Investors should continue monitoring cash flow confirmation and the response of leading groups before the trend broadens.
This data is for analytical and informational purposes only; it is not investment advice.