Trading Session Overview
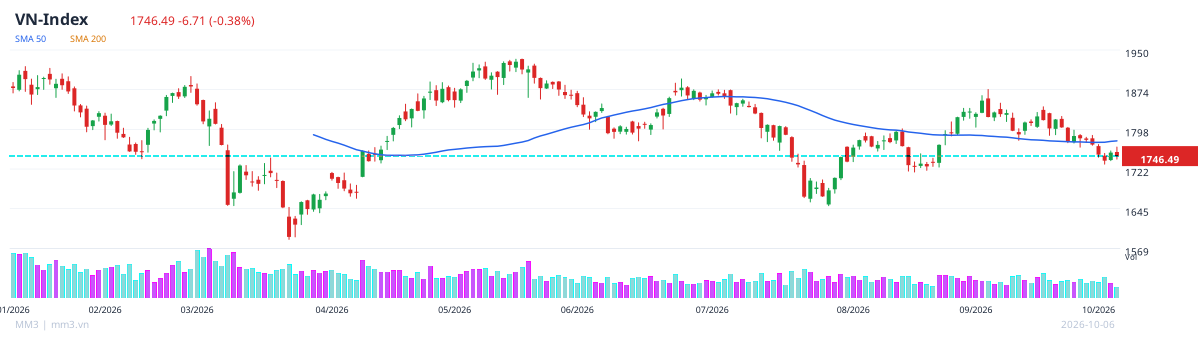
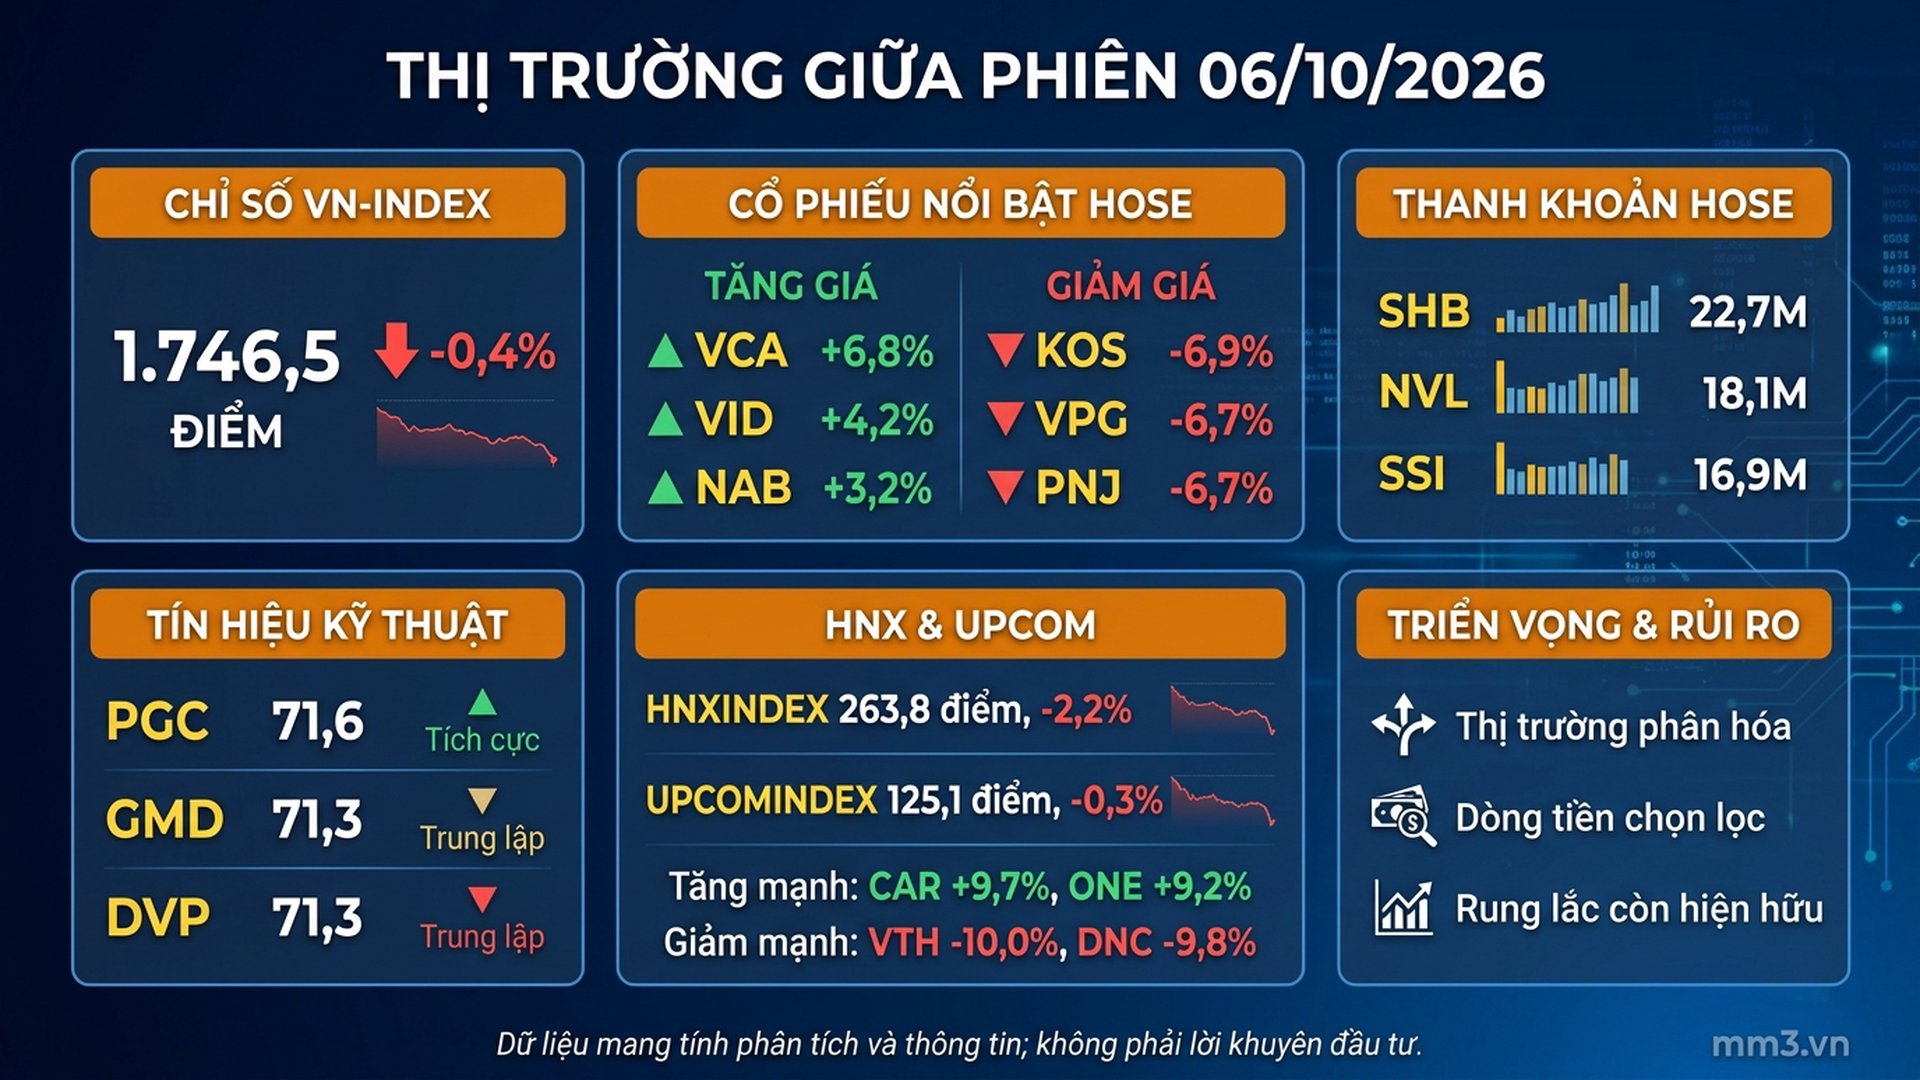
At midday on 06/10/2026, the Vietnamese stock market recorded a broad-based, mild correction. The VN-Index closed the morning session at 1,746.5 points, down 0.4%, while the HNX-Index fell more sharply to 263.8 points, a decline of 2.2%. The UPCOM-Index also slipped to 125.1 points, losing 0.3%.
Market breadth tilted toward decliners as selling pressure appeared across many sectors, although individual stocks still showed clear divergence. Liquidity on HOSE remained notable, led by SHB, NVL and SSI, suggesting that capital has not exited the market but is rotating into selective opportunities.
| Index | Points | Change | Liquidity |
|---|---|---|---|
| VN-Index | 1,746.5 | -0.4% | 317.7M |
| HNX-Index | 263.8 | -2.2% | 39.4M |
| UPCOM-Index | 125.1 | -0.3% | 12.1M |
From a technical perspective, a few individual stocks still maintained positive signals with high composite scores, including PGC, GMD and DVP. Even so, the overall index picture still points to short-term volatility risk, as decliners continue to dominate.
Notable Stock Groups
Among the strong gainers on HOSE, a few standout individual stocks emerged. Leading the pack was VCA, up 6.8%, followed by VID, up 4.2%, and NAB, up 3.2%.
On the opposite side, profit-taking pressure concentrated on several heavily sold stocks, including KOS at -6.9%, VPG at -6.7% and PNJ at -6.7%. The steep declines in these names show that divergence remains very wide, even within the same trading session.
- VCA: +6.8%
- VID: +4.2%
- NAB: +3.2%
- KOS: -6.9%
- VPG: -6.7%
- PNJ: -6.7%
In terms of liquidity, SHB traded 22.7 million shares, NVL reached 18.1 million shares, and SSI reached 16.9 million shares. These stocks attracted substantial capital flows amid a market that is diverging sharply.
Sector Analysis
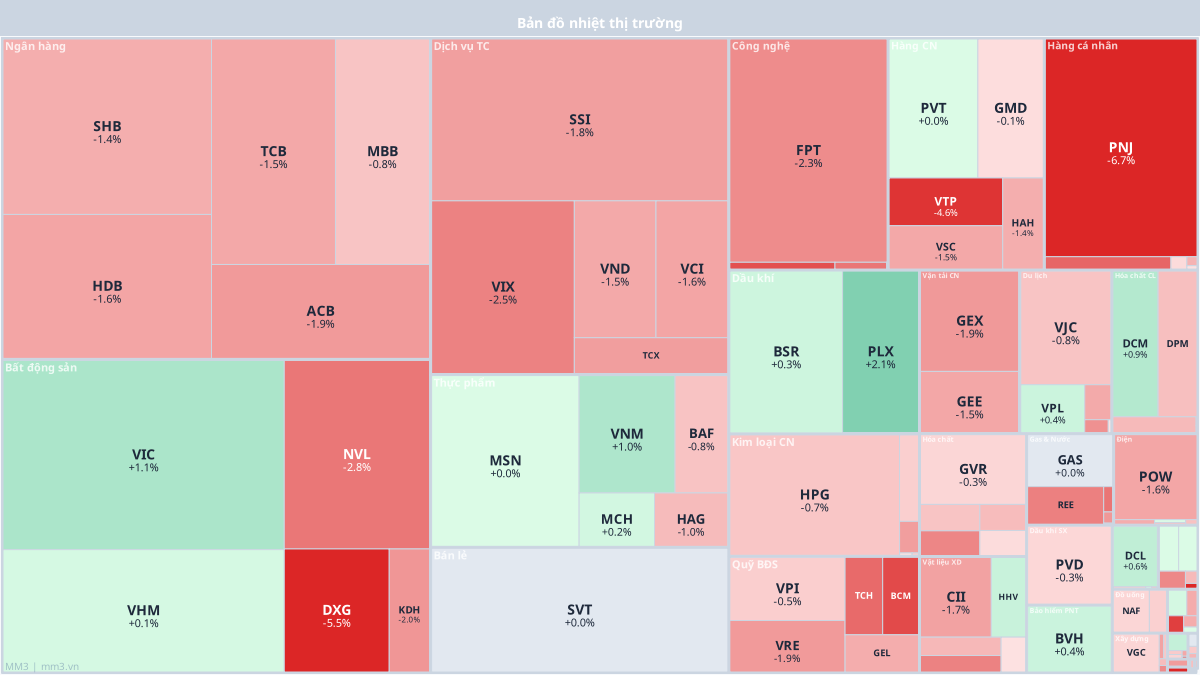
The banking sector generally faced correction pressure, with many HOSE constituents declining. Stocks such as SHB, HDB, TCB, MBB and ACB were all slightly to moderately lower, reflecting cautious sentiment among blue-chip names.
In real estate, the picture was more mixed, with VIC up 1.1% and VHM edging up 0.1%, while NVL fell 2.8%, DXG lost 5.5% and KDH dropped 2.0%. This shows that capital remains highly selective among stocks within the same sector.
Financial services continued to weaken, with SSI, VIX, VND, VCI and TCX all declining. Conversely, sectors such as food, retail, oil and gas, and insurance still had isolated bright spots, but not enough to reverse the overall market trend.
| Sector | Representative stocks | Performance |
|---|---|---|
| Banking | SHB, HDB, TCB, MBB, ACB | Slightly to moderately down |
| Real estate | VIC, VHM, NVL, DXG, KDH | Strongly divergent |
| Financial services | SSI, VIX, VND, VCI, TCX | Weaker than the market |
Several notable technical signals include PGC with a composite score of 71.6, GMD at 71.3, DVP at 71.3, ORS at 67.2, and BVH at 65.7. These stocks are showing a more positive short-term trend than the rest of the market.
Outlook
In the second half of the session, the market is likely to remain divided, with cash flow favoring stocks that have stronger price bases and better technical signals. The 1,746.5-point level of the VN-Index is a key zone to watch closely, as the index is under mild correction pressure.
With the HNX-Index falling more sharply, sentiment in the small- and mid-cap segment could be even more volatile than the rest of the market. Investors should continue to monitor the strength of cash flow and how leading stocks in the banking, real estate, and financial services groups respond before a clearer rebound takes shape.
This data is for analytical and informational purposes only; it does not constitute investment advice.