Trading Session Overview
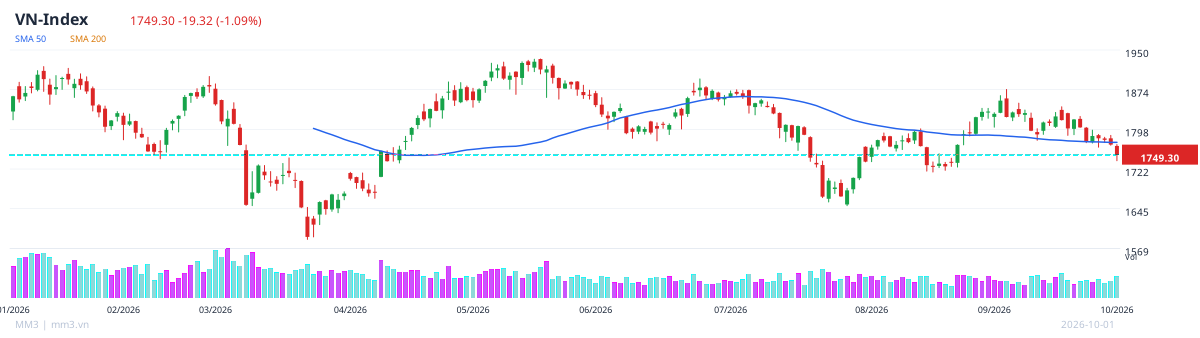
The 01/10/2026 session closed with broad-based corrective action as VNINDEX fell 19.3 points, or 1.1%, to 1,749.3 points. Market-wide liquidity remained high with 638.5 million shares matched, indicating that money flow remains active but leans toward selectivity rather than broad-based spread.
Market breadth tilted toward declines on both major exchanges. On HOSE, leading names still included strong gainers such as BFC, TNC, HSL, DCL and NHA, while many other stocks faced heavy profit-taking pressure, including PNJ, PET, PNC, CCC and KOS.
Notable Stocks
| Ticker | Change | Price | Volume |
|---|---|---|---|
| BFC | +6.9% | 53,900 | 500,300 |
| TNC | +6.9% | 28,600 | 100 |
| HSL | +6.9% | 9,440 | 3.7 million |
| DCL | +6.9% | 46,500 | 1.5 million |
| NHA | +6.9% | 7,290 | 659,500 |
| PNJ | -7.0% | 24,750 | 1.7 million |
| PET | -6.9% | 53,000 | 540,500 |
| PNC | -7.0% | 21,950 | 300 |
| CCC | -7.0% | 5,890 | 7,700 |
| KOS | -6.8% | 15,800 | 2,500 |
The most liquid stocks on HOSE were SHB with 34.6 million shares, VIX with 26.7 million shares, and SSI with 22.0 million shares. This signals that money flow still favors speculative names and stocks highly sensitive to market swings.
Sector Analysis
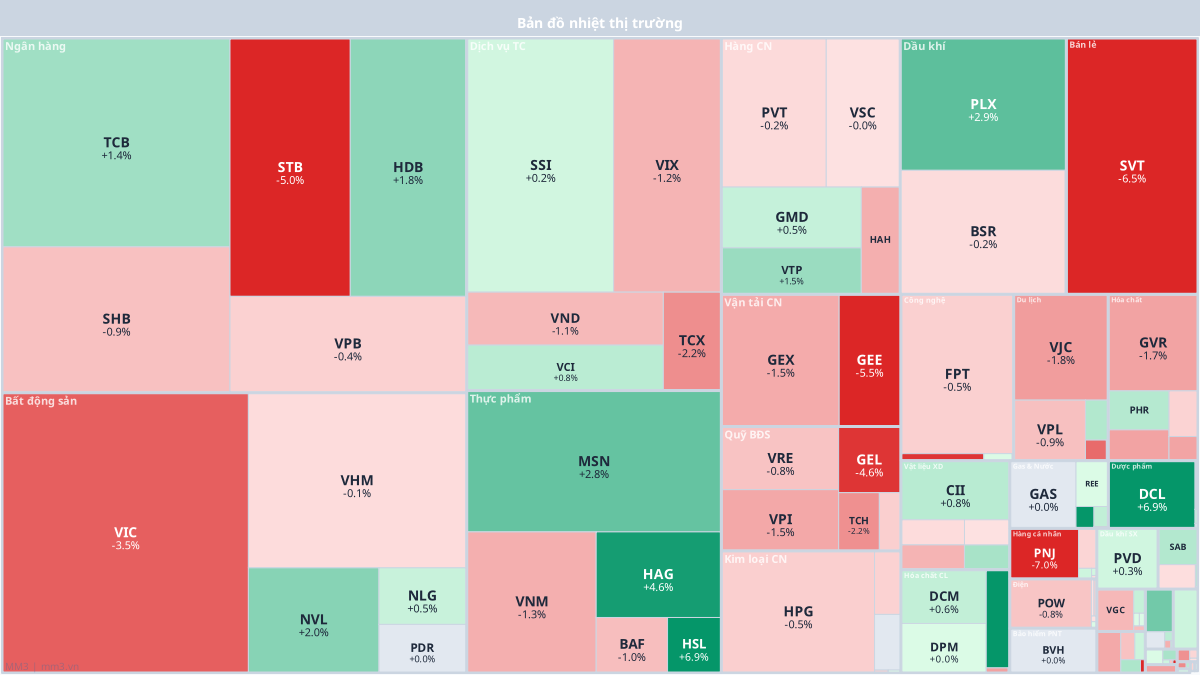
The banking sector continued to diverge clearly. TCB rose 1.4% to 33,000 VND on volume of 17.1 million shares, HDB gained 1.8% to 28,000 VND, while SHB fell 0.9% to 11,350 VND and STB dropped 5.0% to 70,300 VND.
In financial services, SSI edged up 0.2% to 20,150 VND; VIX declined 1.2% to 12,150 VND; VND fell 1.1% to 13,700 VND; and VCI rose 0.8% to 19,500 VND. These moves suggest that money flow in the securities sector remains active, but not yet strong enough to form a consensus uptrend.
In the food sector, MSN stood out with a 2.8% gain to 70,900 VND and HAG rose 4.6% to 14,750 VND, while VNM fell 1.3% to 58,600 VND. In pharmaceuticals, DCL surged 6.9% to 46,500 VND, becoming one of the most notable bright spots of the session.
In oil and gas, PLX rose 2.9% to 36,650 VND, while BSR was nearly unchanged. The retail sector diverged sharply as MWG edged up 0.3% while PET fell 6.9%, reflecting profit-taking pressure on some highly volatile stocks.
Outlook
Session data shows the short-term trend still leans toward correction, but buying demand in some sectors and individual stocks remains strong enough to sustain technical rebounds. Positive signals such as TVS, SMB, and PVT, with MACD and EMA structures tilting bullish, suggest the market has not entirely lost its capacity to recover.
In the near term, the 1,750-point zone of VNINDEX is an important equilibrium level to watch. If liquidity continues to hold and breadth improves in the leading groups, the probability of a technical recovery scenario would be higher; conversely, selling pressure may persist for longer if selling in large-cap stocks has not yet cooled.
This data is for analytical and informational purposes only; it does not constitute investment advice.